
A leasing company in Bangladesh is a finance company licensed by Bangladesh Bank that funds vehicles, machinery and equipment while keeping ownership until the lease ends. Since the Finance Company Act 2023 replaced the 1993 law, both the rules for these companies and the remedies against defaulting lessees have changed.
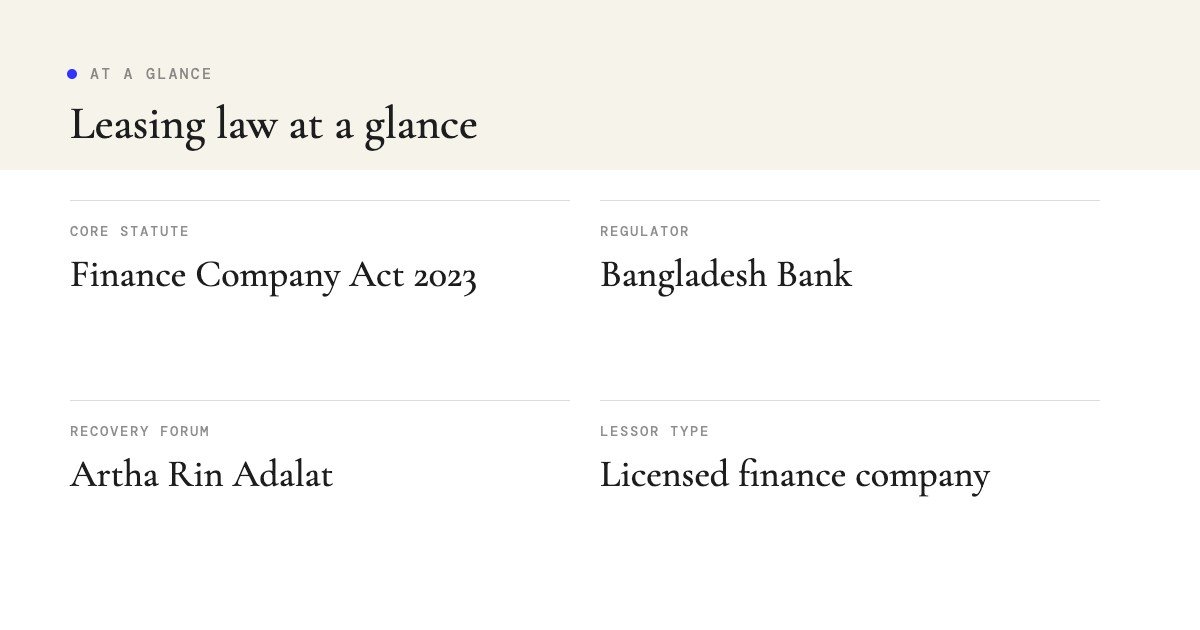
- Leasing is a "financing business" that only Bangladesh Bank-licensed finance companies and banks may carry on; the Finance Company Act 2023 replaced the Financial Institutions Act 1993.
- Running a financing business without a licence can now attract up to seven years' imprisonment, a fine of up to Tk 1 crore, or both.
- The lease agreement, not a separate leasing statute, governs most of the parties' rights; the Contract Act 1872 and, for land and buildings, the Transfer of Property Act 1882 fill the gaps.
- Finance companies recover defaulted leases mainly through the Artha Rin Adalat, and the 2023 Act adds tough consequences for wilful defaulters.
- Bangladesh Bank has moved to liquidate several failed finance companies under the Bank Resolution Ordinance 2025, so lessees should know what happens to their lease if the lessor fails.
What a leasing company in Bangladesh is
In everyday language, a "leasing company" is any business that provides assets on lease. In Bangladeshi regulation, the term usually means a non-bank financial institution, now called a finance company, that offers lease finance alongside term loans and deposits. Many of the country's older finance companies began as leasing specialists and still carry "leasing" in their names.
The economics of a leasing company in Bangladesh are simple. The leasing company buys the asset the customer chooses, such as a delivery truck, a generator or a production line, and lets the customer use it in return for regular rentals. The lessor keeps legal ownership during the lease, which is its main security. At the end, the customer may buy the asset for a nominal or agreed value, return it, or renew the lease.
For small and medium businesses, a leasing company in Bangladesh is often easier to access than a bank term loan, because the asset itself secures the deal. For the lessor, ownership makes recovery easier, provided the lease is properly documented.
Who may offer leases
Leasing for profit as a financing business is regulated. Scheduled banks may offer lease finance under their own licences. Any other business that wants to operate as a leasing company in Bangladesh needs a finance company licence from Bangladesh Bank. An ordinary trading company that rents out its own equipment occasionally is in a different position from one that finances third-party assets as a business; if in doubt, take advice before launching a leasing product.
The legal framework for a leasing company in Bangladesh
There is no single "Leasing Act" in Bangladesh. The rules come from regulatory law, which governs the lessor, and private law, which governs the lease.
Regulatory law
- Finance Company Act 2023. Passed by Parliament on 1 November 2023, it repealed the Financial Institutions Act 1993. It defines financing business to include leasing, requires a Bangladesh Bank licence and sets governance, lending and enforcement rules.
- Bangladesh Bank directions. The Department of Financial Institutions and Markets issues circulars on capital, provisioning, loan classification, disclosure and customer treatment.
- Bank Resolution Ordinance 2025. The framework Bangladesh Bank has used to resolve and liquidate failed finance companies. Parliament passed a Bank Resolution Bill on 10 April 2026; we have not yet seen the final Act text.
- Deposit Protection Bill 2026. Passed by Parliament in April 2026, it brings finance companies into deposit protection for the first time, with membership required by 1 July 2028.
Private law
- Contract Act 1872. Governs equipment and vehicle leases, including the bailment rules on the care and return of goods.
- Transfer of Property Act 1882 and Registration Act 1908. Govern leases of land and buildings; a lease of immovable property from year to year or for more than a year must be made by registered instrument.
- Companies Act 1994. Where a corporate lessee also gives a mortgage or other charge as security, the charge must be registered with RJSC within 21 days of creation under section 159.
- Artha Rin Adalat Ain 2003 and Negotiable Instruments Act 1881. The main recovery tools for finance companies.
Some documents and commentary still refer to the "Financial Institutions Act". For leases signed from late 2023 onwards, check that the lease, guarantees and board resolutions refer to the Finance Company Act 2023. Outdated references rarely invalidate a lease, but they invite arguments in recovery proceedings.

Key provisions of the Finance Company Act 2023
The 2023 Act was designed to clean up a sector damaged by large-scale defaults and governance failures. Several provisions matter directly to anyone dealing with a leasing company in Bangladesh, whether as customer, depositor or investor.
Licensing and unlicensed business
Only licensed entities may carry on financing business, which includes taking term deposits, lending, investing and leasing. Bangladesh Bank can investigate suspected unlicensed operators, take control of their assets and shut them down. The maximum punishment for unlicensed operation rose from two years and a fine of Tk 5 lakh under the 1993 law to seven years and a fine of up to Tk 1 crore, or both.
Wilful defaulters
The Act introduces a statutory concept of wilful default, covering a borrower who does not repay despite being able to, who uses funds for a purpose other than the one stated, or who obtained finance using false documents. As reported when the bill was tabled, wilful defaulters face criminal proceedings if they do not pay within a set period, and can be barred from foreign travel and lose their trade licence.
Governance and lending limits
- No individual, together with family members, may directly or indirectly hold more than 15% of a finance company's shares.
- Unsecured lending to an individual is capped at Tk 10 lakh unless Bangladesh Bank sets another limit.
- Interest cannot be waived in full, and partial waivers need Bangladesh Bank approval.
- Fines on finance companies that lend in breach of the rules were increased.
Existing companies were given time to comply after enactment. Confirm the current position on any transitional point with Bangladesh Bank's latest directions.
Types of leases and how they differ
For a leasing company in Bangladesh and its customers, the label on the document matters less than its substance. Courts, tax authorities and auditors look at who carries the risks and rewards of the asset.
| Structure | How it works | Typical use |
|---|---|---|
| Finance lease | Rentals cover the asset's cost plus return; lessee bears most risks; option to buy at the end | Machinery, vehicles, production lines |
| Operating lease | Shorter term; lessor keeps residual value risk and often maintenance | IT equipment, generators, fleet vehicles |
| Hire purchase | Ownership passes automatically after the final instalment | Vehicles and consumer durables |
| Sale and leaseback | Business sells an existing asset to the lessor and leases it back | Releasing cash tied up in equipment |
| Lease of premises | Lease of land or buildings under the Transfer of Property Act 1882 | Factories, warehouses, offices |
Accounting and tax
Bangladesh follows IFRS, so most leases written by a leasing company in Bangladesh appear on the lessee's balance sheet under IFRS 16 as a right-of-use asset and a lease liability. Tax treatment of rentals, depreciation and VAT on lease services depends on the Income Tax Act 2023, the VAT and Supplementary Duty Act 2012 and the current Finance Act. Rates change regularly, so take tax advice on the specific structure before signing.
Terms to check before signing a lease
A lease from a leasing company in Bangladesh is usually on the lessor's standard form. Standard does not mean non-negotiable. These are the clauses we review first.
- Rentals and rate. Is the rate fixed or floating? If floating, what benchmark applies and how often can it change? Since the SMART reference rate was abolished in May 2024, lending rates have been market-based.
- Ownership and title transfer. When and how does title pass, and what documents will the lessor deliver at the end?
- Insurance and loss. Who insures, for what cover, and what happens to rentals if the asset is destroyed?
- Maintenance and use. Who maintains the asset, and are there limits on location, use or subletting?
- Events of default. Which breaches allow termination, and is there a grace period or cure right?
- Early termination. How is the termination amount calculated, and are there prepayment charges?
- Repossession. What notice must the lessor give, and how will the asset be valued and sold?
- Guarantees and cheques. Are personal guarantees and post-dated cheques required, and when may cheques be presented?
Many lessees sign a bundle of undated post-dated cheques at the start. If the lease later goes into dispute, those cheques can be presented and dishonoured, exposing directors to criminal proceedings under the Negotiable Instruments Act 1881. Agree in writing how and when the cheques may be used. Our guide to cheque dishonour in Bangladesh explains the risk.
Taking a lease from a leasing company in Bangladesh, step by step
Dealing with a leasing company in Bangladesh is usually quicker than taking a bank term loan, but each step has a legal point attached. Follow this sequence to avoid problems later.
- Verify the lessor. Confirm the company holds a current Bangladesh Bank licence and check its recent financial reports and any regulatory action.
- Choose the structure. Decide between finance lease, operating lease or hire purchase with your accountant, considering tax and balance sheet effects.
- Negotiate the term sheet. Agree rentals, rate basis, tenor, down payment, termination value and security.
- Review the documents. Read the lease, guarantees, cheque undertakings and any mortgage or hypothecation documents.
- Register what must be registered. Record the lessor's interest where required, for example on vehicle registration, and register any company charge with RJSC within 21 days.
- Perform and keep records. Pay on time, keep receipts and annual statements, and keep insurance current.
- Close out properly. On the final payment, obtain the title transfer or release documents and return any unused cheques.
Default, repossession and recovery
When rentals stop, a leasing company in Bangladesh has several remedies. Lessees should know them too, because the way a lessor uses them can itself be challenged.
Artha Rin Adalat
Finance companies may sue in the Artha Rin Adalat under the Artha Rin Adalat Ain 2003, the specialist money loan court. The Act includes settlement procedures and limits on the defendant's ability to appeal without deposits, which makes it an effective forum for lessors. Lessees with genuine disputes over the amount claimed should raise them early and document them.
Repossession
Ownership of the asset gives the lessor the right to recover it on termination. That right must be exercised according to the contract and the law. Taking assets by force, intimidation or without the notice the lease requires can expose the lessor and its agents to civil and criminal liability. The safer course is written notice, an inventory and, where the lessee resists, a court order.
Cheques and wilful default
Dishonoured cheques can be prosecuted under the Negotiable Instruments Act 1881. Under the Finance Company Act 2023, a lessee classified as a wilful defaulter faces additional sanctions. Lessees in genuine financial difficulty should seek a documented reschedule rather than simply stopping payment. Our restructuring practice advises on rescheduling and workouts.
Lessee rights and complaints
Lessees are not without protection. A leasing company in Bangladesh must disclose its charges, follow Bangladesh Bank's directions on fair treatment of customers, and give accurate statements of account.
- Ask for a full repayment schedule and an annual statement, and check that charges match the lease.
- If a dispute arises, complain in writing to the lessor's complaints unit first and keep the acknowledgement.
- If the lessor does not resolve the complaint, Bangladesh Bank operates a customer complaints channel for regulated institutions.
- For contractual disputes, consider negotiation, mediation or, where the lease provides for it, arbitration before litigation.
When a leasing company fails
The sector has suffered serious failures, and choosing a sound leasing company in Bangladesh now matters more than ever. In late 2025 Bangladesh Bank's board approved liquidation proceedings for distressed finance companies under the Bank Resolution Ordinance 2025, and reports in January 2026 named nine institutions facing that process, several of them leasing companies. Individual depositors were promised the return of principal with government support, while institutional depositors depend on recoveries.
What lessees should do
The liquidation of a leasing company in Bangladesh does not cancel its leases. The lessee's obligation to pay rentals usually continues, but payments should go only to the account designated by the liquidator or Bangladesh Bank. Keep evidence of every payment. At the end of the lease, the title transfer or release must come from the liquidator, so contact them early. Lessees who are also depositors of the failed company should take advice before attempting any set-off.
What depositors and lenders should do
Depositors and lending banks should file claims promptly with the appointed liquidator and keep copies of deposit receipts and statements. The Deposit Protection Bill 2026 brings finance companies into the deposit protection scheme in future, with coverage of up to Tk 2 lakh per depositor, but membership for finance companies is not required until 1 July 2028.
Foreign investors and cross-border leasing
Foreign investors look at the sector from two angles: owning or partnering with a leasing company in Bangladesh, or leasing assets into Bangladesh from abroad.
Investing in a finance company
Setting up or acquiring a finance company needs Bangladesh Bank's licence or approval, and the Finance Company Act 2023 imposes fit-and-proper, governance and shareholding rules, including the 15% cap for an individual and family. Capital requirements are set by Bangladesh Bank and should be confirmed at the time of application. Given the sector's recent failures, due diligence on asset quality and related-party exposure is essential before buying into an existing company.
Leasing from abroad
Leasing high-value assets such as aircraft, ships or specialised machinery from a foreign lessor involves payments abroad, so it must fit within the foreign exchange rules or receive Bangladesh Bank approval. Customs, VAT and withholding tax on lease rentals also need checking. A local leasing company in Bangladesh can sometimes act as intermediary, but the structure should be agreed with the authorised dealer bank before the contract is signed. Our foreign direct investment practice advises on these structures.
Frequently asked questions about leasing company in Bangladesh
Which law governs leasing companies in Bangladesh?
The Finance Company Act 2023, which replaced the Financial Institutions Act 1993, together with Bangladesh Bank's directions. The lease itself is governed by the Contract Act 1872 and, for land and buildings, the Transfer of Property Act 1882.
Does a leasing business need a licence?
Yes, if it carries on leasing as a financing business. A Bangladesh Bank finance company licence is required unless the entity is a scheduled bank. Unlicensed operation can attract up to seven years' imprisonment and a fine of up to Tk 1 crore.
Can a leasing company take back the asset without a court order?
It may recover its own asset on termination in line with the lease, but it must follow the contract's notice requirements and may not use force or intimidation. Where the lessee resists, a court order is the safer route.
What happens to my lease if the leasing company is liquidated?
The lease normally continues. Pay rentals only to the account the liquidator designates, keep records, and obtain title transfer or release documents from the liquidator when the lease ends.
Is a vehicle lease the same as a car loan?
Not legally. Under a lease or hire purchase, the leasing company owns the vehicle until the final payment; under a loan, you own it and the lender holds security. The difference affects tax, accounting and recovery.
Must a lease of premises be registered?
A lease of immovable property from year to year, or for more than one year, must be made by a registered instrument under the Transfer of Property Act 1882 and the Registration Act 1908.
How we can help
We act for finance companies, banks, lessees and investors on every stage of a lease: structuring and documenting lease programmes, reviewing standard terms, regulatory questions under the Finance Company Act 2023, Artha Rin recovery and defence, and claims in finance company liquidations. Learn more about our asset finance and leasing practice.
Signing, enforcing or disputing a lease?
We review lease documents against current law and Bangladesh Bank directions, and represent lessors and lessees in recovery and liquidation matters.
Book a consultationAsset finance practicePrimary sources: the Finance Company Act 2023, Contract Act 1872, Transfer of Property Act 1882 and Artha Rin Adalat Ain 2003 on the Laws of Bangladesh portal; finance company directions and resolution notices from Bangladesh Bank; charge registration through the Registrar of Joint Stock Companies and Firms.
This article is general information about Bangladeshi law as of 2026 and is not legal advice. Laws, directions and procedures change; confirm current requirements with Bangladesh Bank, the lessor or a qualified lawyer before acting.


0 Comments